By A.A Taofeek.
1.0 INTRODUCTION
Generally, banking and financial sectors have witnessed some significant changes in recent time. These changes, however, have affected the traditional modus operandi of banks and financial sector. Financial sectors have benefited from major substantial advances in all technological operations. The emergence of what is now commonly called fintech has become a major shake-up that put banking and financial sector into a test of time. Although technological innovations are not alien to the banking industry, the current development is, in some ways, quite distinct. It is germane to state here that recent financial technologies were introduced by nonbank startup companies to deliver financial services, which is in direct competition with bank developments. It is important to note that majority of these innovations have occurred in a relatively short period and are still continuing in earnest.
2.0 WHAT IS DIGITAL DISRUPTION IN BANKING AND FINANCIAL SECTOR?
The term “digital disruption” in the context of the banking industry and financial sector describes the substantial adjustments and transformations brought about by technology and digital innovation. It covers the effects of digital technologies on conventional banking procedures, corporate strategies, client expectations, and general industry dynamics.
Put simply, digital disruption in banking and financial sector is a revolution of banking industry. This revolution, however, includes the rise of online and mobile banking, the use of digital payment systems, the introduction of fintech companies, the emergence of new financial products and services, as well as the emergence of blockchain technology.
3.0 IMPACTS OF DIGITAL DISRUPTION IN BANKING AND FINANCIAL SECTOR
The impacts of digital disruption in the banking and financial industry is largely felt in two different ways; positive and negative. Each way shall be briefly highlighted below:
3.1 Positive Impact
Arguably, digital disruption has brought some customers’ satisfactions to the banking industry. Customers now have greater convenience and smooth accessibility as a result of digital disruption which enables them to do banking transactions whenever and wherever they like. As a result of streamlined operations and a decreased reliance on physical branches made possible by digital platforms, banks have also seen an improvement in efficiency and cost-effectiveness.
Covid-19 as a case study, during the lockdown period, people were able to carry out transactions without having to take the risk of queuing up at their bank physical branches. This was achievable through the use of online banking, Mobile App among others.
3.2 Negative Impact
It is well known that banking and financial industry have suffered a major setback from the emergence of technology. The traditional banking system is losing its value. Indeed, with the development of digital payment platforms, such as Opay and Palmpay, the provision of payment services is evolving rapidly and disrupting traditional channels provided by banks, such as branch offices. Note that Opay and Palmpay belong to technology-based companies.
Similarly, the process of automation and digitalization may lead to job losses in traditional banking roles; hence the workforce will drastically reduce and may lead to inevitable loss of the experts in the banking sector.
It is germane to analyze the banking services which are largely being affected and most likely continuing to be affected by the emergence of these tech-giant companies (i.e The Fintech). Basically, payment and remittances, micro and small loans, vehicle loans are currently being affected. The swift payment method, few records of failed transactions of the fintech, for instance, Opay has greatly diverted traditional bank customers to the use of this Fintech company.
4.0 Sustainable Framework
To ensure sustainability and having edge in the financial sector, the banks have to sit tight, restrategize and put forward some policies which include but not limited to the following:
- Digitalizing their service and products:
It is a bitter truth that the future of banking and financial sector relies heavily on digitalization. The swift advancement of technology can not be over emphasized in this area. Banks should invest in modern and sophisticated technologies that will make their product and service more accessible to their customers. The days of relying on opening more branches to satisfy customers are gradually going into exit. Virtually, a larger percentage of these customers wish to solve any banking related issue on their devices at their comfort considering the untold hardship they face on the long queue at the customer service at the physical branch of their banks.
- Cyber Security Enhancement:
Stationed on the (a) above, it should be noted that if banks are going digital, they should invest in robust cyber-security measures, encryption technologies, and real-time threat monitoring to safeguard customers data and transactions. To have a successful plan on the digitalization, it is expected that banks should invest in modern ethical hacking and employ experts in this field to not only adequately but also accurately monitor the imminent threat to their server. This is necessary in order to guarantee the safety of customers data and transactions.
- Skill Development:
Banks should invest in retraining and up-skilling their employees to adapt to new roles in the digital banking landscape. As an emerging area, it is germane that banks should re-train their employees on how to make use of these technologies to fast-track banking services. This will definitely up-skill and upgrade their employees to become useful to these technologies. They should keep their focus on skills that complement technologies related to banking and financial services.
- Cross-Industry Collaboration:
Banks are expected to collaborate with other industries and tech experts to share knowledge, experiences, and best practices for managing digital disruption. As an emerging concept, technologies keep advancing each day, it is however, necessary for the banks and financial sector to have a smooth relationship with tech companies to be aware of the latest technology and the risk attached to it.
- Intellectual Property Rights:
The importance of intellectual property rights in the business arena today can not be over estimated. As a business oriented sector, banks and financial sectors should leverage on their intellectual property rights. This, definitely, will be a means of generating revenue for the industry. This may be done by IP evaluation which will enable the banking industry to have a cognizance of their intellectual property rights and equally gives a warning if they are infringing or about to infringe intellectual property rights of another. Effective management of intellectual property rights by the banks and financial sectors will keep them firm amidst the storm of the global market.
5.0 Conclusion
It is not a gain saying that banks and financial sectors have suffered setback from the current digital disruption. However, to maintain having edge in the financial industry, banks should take holistic approach which includes investment in technology, long-term policy, education, and collaboration. By so doing, the banking and financial sectors will drastically mitigate the downsides of digital disruption and ensure a safer and more inclusive digital financial landscape in the industry.
*A.A Taofeek is a student of Law at the most prestigious Usmanu DanFodiyo University Sokoto and can always be reached via Olamideajibade02@gmail.com || 08085374513
BIBLIOGRAPHY
Atje, R., Setiati, I., & Fadhil, I. (2020) Impacts of Disruptive Technology on Banks. In DISRUPTIVE TECHNOLOGY IN INDONESIAS BANKING SECTOR.
Hsu, S., & Li, J, (2020). Chinas Fintech Explosion: Disruption, Innovation, and Survival. Columbia University Press.
Ifeanyi, N., Techpoint Africa, (Opay, Palmpay and a long line of Chinese investor interests in Africa, 21 November 2019) available at < https://techpoint.africa/2019/11/21/chinese-investor-interest-in-africa/ > accessed 3 September 2023.
[A MUST HAVE] Evidence Act Demystified With Recent And Contemporary Cases And Materials
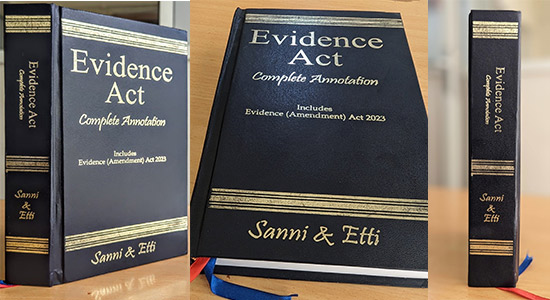
Available now for NGN 40,000 at ASC Publications, 10, Boyle Street, Onikan, Lagos. Beside High Court, TBS. Email publications@ayindesanni.com or WhatsApp +2347056667384. Purchase Link: https://paystack.com/buy/evidence-act-complete-annotation
______________________________________________________________________ “Enhance Legal Practice With Authoritative Reports” — Alexander Payne Offers Comprehensive Law Reports, Spanning Over A Century Of Nigerian Jurisprudence Interested buyers are encouraged to place their orders and enquiries via:
0704 444 4777, 0704 444 4999, 0818 199 9888
Website: www.alexandernigeria.com