
The Federal High Court, presided over by Justice Peter O. Lifu, has nullified provisions of the Delta State Hotel Occupancy, Restaurants and Departmental Stores Consumption Tax Law, 2017, which imposed an additional five per cent consumption tax on transactions already subject to the federal Value Added Tax (VAT) regime.
Justice Lifu declared Sections 3 and 4 of the Delta State law invalid and also set aside Section 7(b), Item 13 of the Schedule to the Taxes and Levies (Approved List for Collection) Act (Amendment) Order No. 77 of 2015.
The court further issued a perpetual injunction restraining the Delta State Attorney-General and Commissioner for Justice, the Delta State Board of Internal Revenue, and their agents or representatives from implementing or enforcing the affected provisions.
The judgment followed a suit instituted by the Nigeria Employers’ Consultative Association (NECA) and Retail Supermarkets Nigeria Limited, operators of Shoprite stores, against the Attorney-General of the Federation, the Delta State Attorney-General and Commissioner for Justice, and the Delta State Board of Internal Revenue.
The plaintiffs, through their counsel, Dr Joseph Nwobike, SAN, of Osborne Law Practice, challenged the constitutionality and validity of the disputed provisions, arguing that the additional consumption tax imposed an overlapping tax burden on goods and services already subject to VAT.
Nwobike led the plaintiffs’ legal team alongside G. D. Nwani, while J. O. Obaje represented the Attorney-General of the Federation. Isaiah Bozimo, SAN, appeared for the Delta State defendants.
In their originating summons, NECA and Shoprite contended that Delta State lacked the legislative competence to impose a separate consumption tax on transactions already covered by the federal VAT regime.
They argued that Sections 3 and 4 of the Delta State law, which provided for the imposition and collection of the five per cent consumption tax, were inconsistent with the federal VAT framework to the extent that both taxes applied to the same transactions.
The plaintiffs also challenged Section 7(b), Item 13 of the Schedule to the 2015 amendment order, maintaining that the provision could not validly authorise a state to impose an additional consumption tax on goods and services already subject to VAT.
According to them, the disputed levy imposed an extra five per cent charge on specified transactions involving restaurants, supermarkets and departmental stores, thereby increasing the tax burden on businesses and consumers.
Shoprite, which operates retail outlets in Delta State and other parts of Nigeria, maintained that the additional tax adversely affected its business operations.
NECA, representing more than 480 corporate members, similarly argued that the levy created overlapping tax obligations for businesses operating within the state.
In opposing the suit, the Delta State defendants maintained that the state consumption tax and federal VAT were legally distinct.
They argued that VAT was imposed at multiple stages of transactions, while the state consumption tax applied at a single stage.
The defendants further contended that Section 4 of the Delta State law excluded VAT from the computation of the consumption tax, thereby preventing double taxation.
However, Justice Lifu rejected the argument that differences in the methods of assessment and collection were sufficient to justify the additional levy.
In determining the dispute, the court examined whether Delta State could lawfully impose a separate consumption tax on transactions already covered by the federal VAT regime.
Justice Lifu considered the Supreme Court’s decision in Attorney-General of Lagos State v. Eko Hotels Limited (2018) 7 NWLR (Pt. 1619) 518, which addressed the relationship between federal VAT legislation and state consumption tax laws.
The court also examined Section 4(5) of the 1999 Constitution, which provides that where a state law is inconsistent with a valid law enacted by the National Assembly, the federal law prevails, and the state law becomes void to the extent of the inconsistency.
Applying the constitutional framework to the disputed provisions, Justice Lifu held that the challenged sections of the Delta State consumption tax law could not stand.
The court consequently nullified Sections 3 and 4 of the Delta State Hotel Occupancy, Restaurants and Departmental Stores Consumption Tax Law, 2017, together with Section 7(b), Item 13 of the Schedule to the Taxes and Levies (Approved List for Collection) Act (Amendment) Order No. 77 of 2015.
Before determining the substantive dispute, the court dismissed preliminary objections raised by the Attorney-General of the Federation and the Delta State defendants, who had challenged its jurisdiction to entertain the suit.
Justice Lifu held that the plaintiffs’ challenge to the validity of the federal amendment order brought the dispute within the constitutional jurisdiction of the Federal High Court under Section 251 of the 1999 Constitution.
The judge therefore assumed jurisdiction and proceeded to determine the substantive claims.
Having found in favour of the plaintiffs, the court granted the reliefs sought against the challenged provisions.
It also issued a perpetual injunction restraining the Delta State Attorney-General and Commissioner for Justice, the Delta State Board of Internal Revenue, and their agents or representatives from implementing or enforcing the invalidated provisions.
The judgment prevents the affected Delta State authorities from continuing to enforce the five per cent consumption tax under the provisions struck down by the court, subject to any subsequent appellate decision.
The ruling represents a victory for NECA and Shoprite in their challenge to the additional consumption tax imposed on transactions already subject to VAT.
It also addresses the constitutional limits of state taxation powers where state legislation conflicts with valid federal legislation.
[A MUST HAVE] Evidence Act Demystified With Recent And Contemporary Cases And Materials
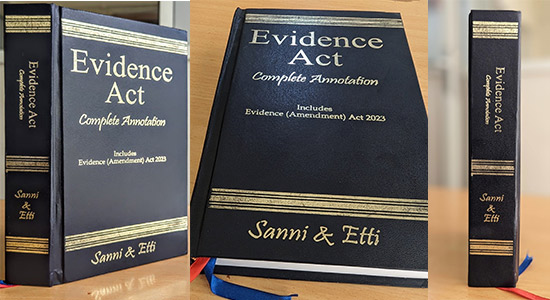
Available now for NGN 40,000 at ASC Publications, 10, Boyle Street, Onikan, Lagos. Beside High Court, TBS. Email publications@ayindesanni.com or WhatsApp +2347056667384. Purchase Link: https://paystack.com/buy/evidence-act-complete-annotation
______________________________________________________________________ “Enhance Legal Practice With Authoritative Reports” — Alexander Payne Offers Comprehensive Law Reports, Spanning Over A Century Of Nigerian Jurisprudence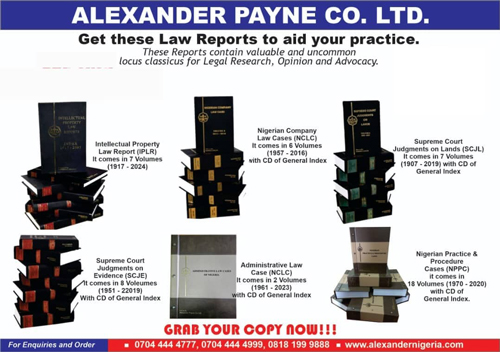 Interested buyers are encouraged to place their orders and enquiries via:
0704 444 4777, 0704 444 4999, 0818 199 9888
Website: www.alexandernigeria.com