
The House of Representatives has passed through second reading a bill to amend the Companies Income Tax Act, aimed at providing adequate security and guarantees for businesses and companies regarding the payment of minimum tax in years when they incur losses.
Sponsored by Hon. Oboku Abonsizeibe Oforji, the member representing Yenagoa/Kolokuma/Opokuma Federal Constituency in Bayelsa State, the bill was read for the second time at plenary on Thursday.
The bill seeks to amend Section 33 of the Principal Act by removing the phrase “results in a loss or where a company’s ascertained total profits” from Section 33, Subsection 1, and by inserting a new Subsection (D) in Section 33(3). The new Subsection 33:3 (D) reads: “Any company in operation that records losses in the assessment year.”
This amendment aims to adjust how companies are assessed for tax purposes, specifically protecting businesses that are operating but incurring losses from having to pay a minimum tax.
The bill proposes an exemption for companies in such situations under the Companies Income Tax Act for each assessment year.
[A MUST HAVE] Evidence Act Demystified With Recent And Contemporary Cases And Materials
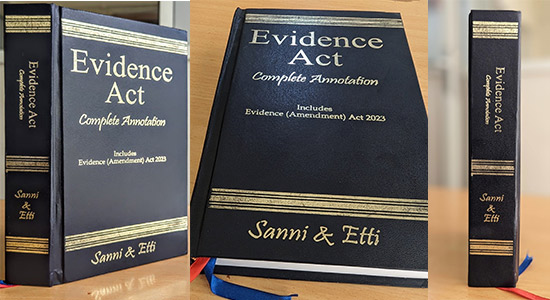
Available now for NGN 40,000 at ASC Publications, 10, Boyle Street, Onikan, Lagos. Beside High Court, TBS. Email publications@ayindesanni.com or WhatsApp +2347056667384. Purchase Link: https://paystack.com/buy/evidence-act-complete-annotation
______________________________________________________________________ “Enhance Legal Practice With Authoritative Reports” — Alexander Payne Offers Comprehensive Law Reports, Spanning Over A Century Of Nigerian Jurisprudence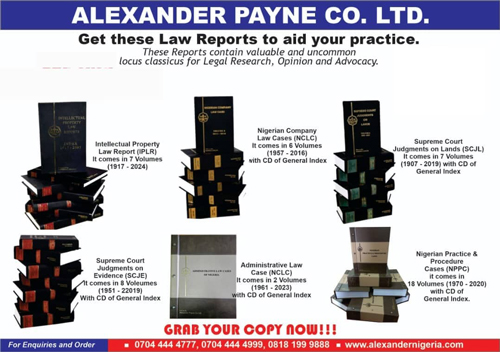 Interested buyers are encouraged to place their orders and enquiries via:
0704 444 4777, 0704 444 4999, 0818 199 9888
Website: www.alexandernigeria.com